


HomeGoods NNN Investor Hub | Cap Rate Trends, Credit Rating Trends, Lease Terms & Due Diligence
Last Year Cap
6.5%
This Year Cap
6.7%
Cap Change
0.3%
Last Year Rating
A
This Year Rating
A
Rating Change
No change
HomeGoods – NNN Cap Rate Trend
Cap Rate Trends
| wdt_ID | wdt_created_by | wdt_created_at | wdt_last_edited_by | wdt_last_edited_at | Tenant | Year | Cap Rate |
|---|---|---|---|---|---|---|---|
| 5779 | admin2 | 2026 04:17 AM | admin2 | 2026 04:17 AM | 7 Brew | 2,020 | 6.5 |
| 5780 | admin2 | 2026 04:17 AM | admin2 | 2026 04:17 AM | 7 Brew | 2,021 | 6.3 |
| 5781 | admin2 | 2026 04:17 AM | admin2 | 2026 04:17 AM | 7 Brew | 2,022 | 6.0 |
| 5782 | admin2 | 2026 04:17 AM | admin2 | 2026 04:17 AM | 7 Brew | 2,023 | 6.3 |
| 5783 | admin2 | 2026 04:17 AM | admin2 | 2026 04:17 AM | 7 Brew | 2,024 | 6.6 |
| 5784 | admin2 | 2026 04:17 AM | admin2 | 2026 04:17 AM | 7 Brew | 2,025 | 6.6 |
| Tenant | Year | Cap Rate |
Credit (what net-lease buyers care about)
Credit Snapshot
HomeGoods
HomeGoods Net Lease: Secure, Essential Investment
HomeGoods is a nationally recognized home furnishings retailer and a leading brand within The TJX Companies, one of the largest off-price retail organizations in the world. This guide reviews cap rates, lease terms, tenant profile, and key due diligence considerations for buyers and sellers.
For 1031 exchange buyers, HomeGoods Ground Lease Properties are important to compare against fee simple HomeGoods assets, as lease structure can materially impact pricing, financing, and long-term resale value.
Investors often target HomeGoods assets for:
• Stable Income Potential
• Strong National Brand Recognition
• Consistent Consumer Traffic
• Attractive 1031 Exchange Compatibility
HomeGoods Ground Lease Properties require close comparison of rent escalations, remaining lease term, extension options, and residual land value versus fee simple ownership.
HomeGoods Ground Lease Properties for 1031 Exchange Buyers
HomeGoods Ground Lease Properties often trade differently than fee simple HomeGoods assets. Buyers should carefully evaluate lease structure, remaining term, renewal options, landlord responsibilities, and reversion rights to understand long-term risk and return.
HomeGoods – Credit Trend (S&P vs Moody’s)
Tenant_Rating_Trend
| wdt_ID | wdt_created_by | wdt_created_at | wdt_last_edited_by | wdt_last_edited_at | TenantKey | Tenant | Year | Moody | SP | Moody_Grade | SP_Grade | Moody_GradeRank | SP_GradeRank |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | admin2 | 2025 03:43 PM | admin2 | 2025 03:43 PM | 7eleveninc | 7-Eleven, Inc. | 2022 | Baa2 | A | Lower Medium Grade | Upper Medium Grade | 5 | 6 |
| 2 | admin2 | 2025 03:43 PM | admin2 | 2025 03:43 PM | 7eleveninc | 7-Eleven, Inc. | 2023 | Baa2 | A | Lower Medium Grade | Upper Medium Grade | 5 | 6 |
| 3 | admin2 | 2025 03:43 PM | admin2 | 2025 03:43 PM | 7eleveninc | 7-Eleven, Inc. | 2024 | Baa2 | A | Lower Medium Grade | Upper Medium Grade | 5 | 6 |
| 4 | admin2 | 2025 03:43 PM | admin2 | 2025 03:43 PM | 7eleveninc | 7-Eleven, Inc. | 2025 | Baa2 | A | Lower Medium Grade | Upper Medium Grade | 5 | 6 |
| 5 | admin2 | 2025 03:43 PM | admin2 | 2025 03:43 PM | 99centsonlystoresllc | 99 Cents Only Stores, LLC | 2022 | Caa2 | CCC+ | Substantial Risk | Substantial Risk | 2 | 2 |
| TenantKey | Tenant | Year | Moody | SP | Moody_Grade | SP_Grade | Moody_GradeRank | SP_GradeRank |
TJX Companies Stock Price (NYSE: TJX)
HomeGoods Investment Market Statistics
AVERAGE SALE PRICE
BUILDING SIZE
AVERAGE NOI
LAND
$/SF RANGE
LEASE TERM SHOWN
HomeGoods Investor Snapshot (Quick Facts)
Origins & Growth (Past)
• Founded in 1992 as a home furnishings retailer
• Expanded nationally through organic growth
• Became a leading brand within The TJX Companies
• Established locations in major retail corridors
• Focused on value-priced home décor and furnishings
• Grew into one of the largest U.S. home goods retailers
Where HomeGoods Stands Today
• Nationwide retail footprint
• Leading home furnishings retailer
• Strong customer traffic volumes
• Corporate-operated store network
• Value-focused home merchandise
• Efficient inventory management
• Continued store expansion and optimization
Where HomeGoods Stands Today
• Inventory Optimization
• Operational Efficiency
• Customer Engagement
• Store Expansion
• Omnichannel Integration
• Home Furnishings Demand
• Value Retailing
• Market Expansion
Why investors buy HomeGoods NNN Properties or HomeGoods ground Lease Properties?
Pros (what buyers like)
- Strong Parent Company
Operated by The TJX Companies, one of the largest off-price retail organizations in the world. - Established National Brand
HomeGoods is a leading home furnishings retailer with strong consumer recognition. - Value-Oriented Retail Model
Discount pricing helps attract customers across various economic conditions. - Consistent Customer Traffic
Frequent shopping visits driven by constantly changing home décor and furnishings inventory. - Prime Retail Locations
Typically located in dominant shopping centers, power centers, and major retail corridors. - Attractive Lease Structures
Long-term NNN and ground leases appeal to passive investors and 1031 exchange buyers.
Cons (what can bite you)
- Lease Structure Variability
Some assets may include landlord responsibilities depending on lease terms. - Flat or Limited Rent Growth
Certain leases contain minimal rent escalations. - Large Box Re-Tenanting Risk
Larger retail spaces can require time and capital to re-lease if vacated. - Retail Industry Competition
Faces competition from furniture stores, home décor retailers, and e-commerce platforms. - Market-Specific Performance Risk
Store performance may vary based on demographics and local competition. - Shopping Center Dependency
Many locations rely on the continued health and occupancy of the surrounding retail center.
Investor Decision Framework (Buy / Hold / Sell)
✓ Strong “Buy Box” for a HomeGoods Net Lease
• 10–15+ years lease term remaining • Absolute NNN or clean NNN lease structure • Strong-performing store in an established trade area • High-traffic retail corridor with excellent visibility • Located within a dominant shopping center or power center • Strong demographics and household income levels • Rent aligned with market fundamentals and replacement cost • Backed by the strength of The TJX Companies
02
⚠ Yellow Flags (Price Accordingly)
• NN or modified NNN lease with landlord responsibilities • Flat rent with limited or no escalations • Oversized retail box that may be difficult to re-tenant • Secondary retail location with weak visibility or access • Aging shopping center or declining trade area • Retail center vacancy or co-tenancy concerns • Weak demographics or slowing population growth • Increased competition from home furnishings retailers and e-commerce channels
Find out more
HomeGoods Background & History
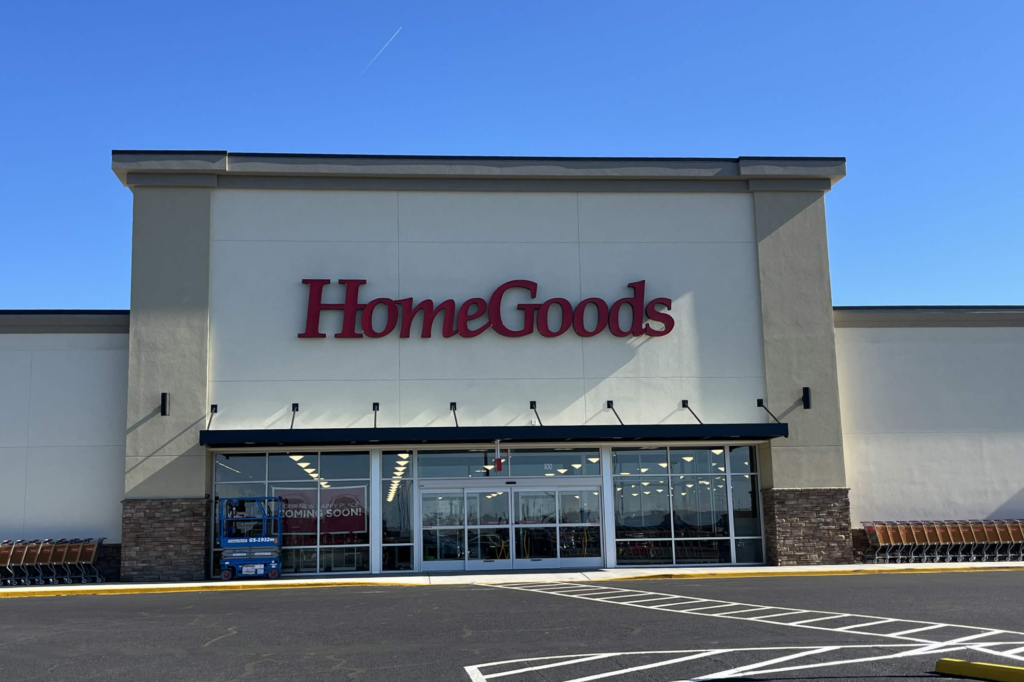
HomeGoods is one of the leading home furnishings retailers in the United States and operates as a major brand within The TJX Companies, a global leader in off-price retail. The company offers a wide assortment of home décor, furniture, kitchenware, bedding, seasonal merchandise, and other home-related products at value-oriented prices.
Since its launch in 1992, HomeGoods has expanded from a specialty home décor retailer into a nationwide chain serving customers across major metropolitan and suburban markets. The brand’s off-price retail model focuses on offering constantly changing assortments of branded merchandise, encouraging repeat visits and consistent customer traffic.
As consumer interest in home improvement, décor, and value-focused shopping has grown, HomeGoods has continued to refine its merchandising strategy, inventory management systems, and supply chain operations to support efficient store performance and long-term growth.
Why HomeGoods Matters to NNN Investors
HomeGoods operates a large nationwide store network and benefits from the financial strength, scale, and operational expertise of The TJX Companies. The retailer’s value-focused merchandising strategy attracts a broad customer base and generates recurring traffic through frequently changing home merchandise assortments and discounted pricing.
Many HomeGoods stores are located within dominant shopping centers, power centers, and established retail corridors. These locations often benefit from strong visibility, convenient access, complementary retailers, and dense population centers that help support customer traffic and long-term real estate value.
The company’s continued focus on inventory optimization, operational efficiency, and disciplined store growth has helped maintain its position as one of the leading home furnishings retailers in North America. This emphasis on value retailing and customer traffic generation helps explain why HomeGoods remains a desirable tenant within the net lease investment market.
What Buyers and Sellers Should Evaluate
For investors evaluating HomeGoods NNN properties, a HomeGoods net lease, or a HomeGoods ground lease, the investment thesis is typically centered on real estate quality, lease structure, and location fundamentals. Buyers often place greater emphasis on trade area strength, store performance, lease economics, and long-term property usability than on brand recognition alone.
Common searches include HomeGoods real estate, HomeGoods cap rate, HomeGoods lease term, HomeGoods tenant profile, and store performance. Ultimately, HomeGoods net lease value is driven by site-specific factors, lease economics, market demographics, and the property’s position within the surrounding retail landscape.
As retail trends continue to evolve, the strongest HomeGoods locations tend to be those situated within established trade areas featuring strong population density, favorable household incomes, excellent visibility, and complementary retailers. Buyers and sellers should evaluate each property individually, including traffic counts, access, co-tenancy, surrounding competition, and lease language that defines landlord responsibilities.
In addition, investors should consider long-term cash-flow durability, lease rollover risk, market conditions, and how the asset may perform across different hold periods and exit strategies.
our team of experts are here for you
Our team helps investors evaluate NNN properties with practical, market-based guidance. In addition, we support buyers and sellers with lease review, pricing analysis, and due diligence strategy.
Whether you are comparing HomeGoods ground lease properties or fee simple HomeGoods assets, we can help you review the details that affect risk and long-term value. As a result, clients can make more confident decisions based on lease structure, location quality, and investment goals.